

If you’re carrying debt in Canada right now, you are far from alone. As of Q4 2024, total consumer debt in the country hit a historic high of $2.56 trillion, according to Equifax Canada — and the average Canadian now carries $21,931 in non-mortgage debt. With credit cards in Canada typically charging 20.99% interest or more, letting debt linger isn’t just stressful. It’s genuinely expensive.
So when you’re finally ready to get serious about paying it off, a natural question comes up: where do you even start? If you have multiple debts — a credit card here, a car loan there, a line of credit you barely touch — should you tackle the smallest balance first, or hunt down the most expensive interest rate?
That question is at the heart of two of the most popular debt repayment strategies in personal finance: the Debt Snowball and the Debt Avalanche. Both methods are structured, proven, and beloved by financial coaches and frugal living communities alike. But they work very differently — and for Canadians juggling high credit card rates, rising living costs, and mortgage pressures, picking the right one can make a meaningful difference.
In this guide, we’ll break down exactly how both methods work, compare them with a real Canadian debt scenario, and help you figure out which approach gives you the best shot at actually becoming debt-free.
If you struggle with motivation and quitting past debt plans, the Debt Snowball is likely your best bet. If you’re disciplined and want to minimize the total interest you pay, the Debt Avalanche wins mathematically.
QUICK ANSWER
What Is the Debt Snowball Method?
The debt snowball method was popularized by American financial author Dave Ramsey, but its appeal has crossed borders — and for good reason. The idea is deceptively simple: list all your debts from smallest balance to largest, and throw every extra dollar at the smallest one while paying the minimum on everything else. When the smallest debt is gone, you roll the payment you were making on it into the next smallest debt. Repeat until everything is paid off.
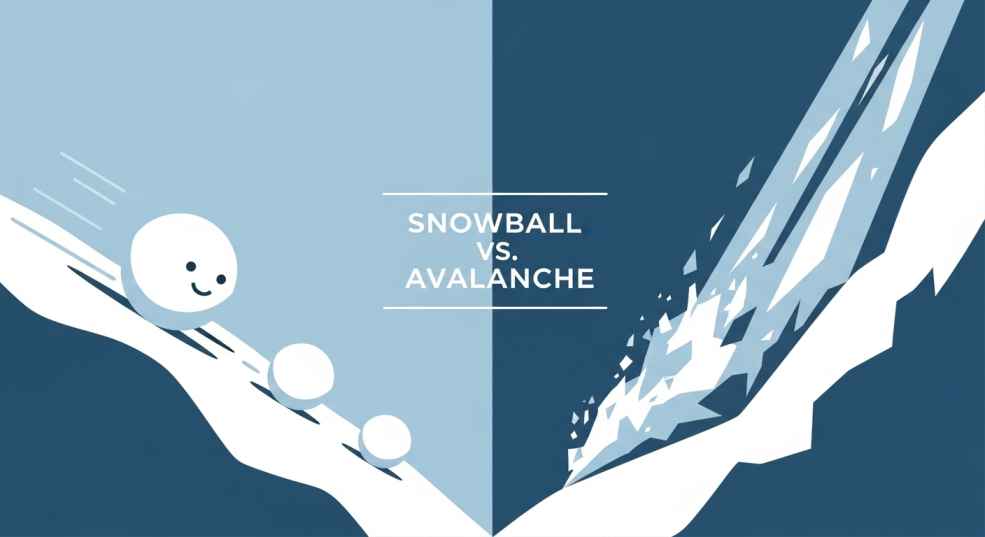
The name comes from the image of a snowball rolling down a hill, picking up snow and momentum as it goes. Your payments — and your confidence — build as each debt disappears.
How the Snowball Method Works: Step by Step
- List all your debts from smallest balance to largest (ignore interest rates for now).
- Make minimum payments on every debt except the smallest one.
- Put every extra dollar you can find toward the smallest debt.
- When the smallest debt is paid off, take its full payment and add it to the minimum payment on the next smallest debt.
- Repeat until all debts are gone.
Why the Snowball Works Psychologically
Here’s the key insight behind the snowball: paying off debt is as much a behavioural challenge as a mathematical one. Research cited by Credit Canada found that roughly 72% of people who start the snowball method stick with it — compared to around 58% for the avalanche method. The reason? Quick wins.
Seeing a debt completely disappear from your list — even a small one — triggers a real sense of progress and accomplishment. That psychological reinforcement keeps you engaged. And for many Canadians, staying engaged is the hardest part. It doesn’t matter how mathematically optimal a strategy is if you abandon it after three months.
🍁 FrugalLiving.ca Take: The snowball method is not irrational. The ‘cost’ of extra interest you might pay is often the price of a system you’ll actually follow through on. Behaviour beats math if the math plan never gets executed. |
What Is the Debt Avalanche Method?
The debt avalanche (sometimes called ‘debt stacking’) takes the opposite philosophical approach. Instead of chasing emotional wins, it chases efficiency. You list all your debts from highest interest rate to lowest, and direct all extra money toward the most expensive debt first, regardless of its balance size.
The logic is straightforward: your highest-interest debt is costing you the most money every single month. The faster you eliminate it, the more money you free up — and those savings compound over time, like an avalanche picking up speed.
How the Avalanche Method Works: Step by Step
- List all your debts from highest interest rate to lowest (ignore balance size).
- Make minimum payments on every debt except the highest-rate one.
- Throw every extra dollar at the highest-interest debt.
- When it’s paid off, redirect its full payment to the next highest-rate debt.
- Repeat until debt-free.
The Avalanche’s Mathematical Edge
The avalanche method is mathematically superior in almost every scenario where interest rates differ significantly. When one debt charges 29.99% (a common Canadian retail credit card rate) and another charges 7.49% (a typical auto loan), tackling the 29.99% debt first dramatically reduces the interest accruing each month. Over a multi-year payoff journey, that difference can mean saving thousands of dollars and months — sometimes years — of extra payments.
However, this advantage narrows considerably when your debts have similar interest rates. If your three debts all hover around 9–12%, the mathematical difference between the snowball and avalanche is marginal, and the snowball’s motivational edge may outweigh the small interest savings.
Debt Snowball vs. Debt Avalanche: A Direct Comparison
Here is how the two methods stack up across the factors that matter most for Canadian debt holders:
Factor | Debt Snowball | Debt Avalanche |
Priority Order | Smallest balance first | Highest interest rate first |
Motivation Style | Quick psychological wins | Long-term mathematical discipline |
Interest Savings | Lower savings | Maximum savings |
Time to Debt-Free | May take slightly longer | Potentially faster |
Best For | Motivation-driven people | Math-minded, disciplined people |
Typical Canadian Context | Multiple smaller debts (retail cards, BNPL) | High-interest credit card debt (20.99%+) |
Adherence Rate* | ~72% stick with it | ~58% stick with it |
Risk | Paying more interest long-term | Losing motivation early |
*Adherence rate data sourced from Credit Canada research.
The avalanche method saves more money on paper. But the snowball method often saves more money in practice — because people actually finish it.
KEY INSIGHT
A Real Canadian Debt Scenario: Let’s Run the Numbers
Let’s put both methods to the test using a realistic Canadian debt profile. Meet Sarah — a 34-year-old in Mississauga, Ontario, who has accumulated the following debts:
Debt | Balance | Interest Rate | Min. Payment |
TD Visa Credit Card | $4,200 | 20.99% | $84/mo |
Retail Store Card | $800 | 29.99% | $24/mo |
Car Loan (RBC) | $8,500 | 7.49% | $190/mo |
Personal Line of Credit | $3,100 | 9.70% | $62/mo |
TOTAL | $16,600 | — | $360/mo |
Sarah has $500/month of extra money beyond her minimum payments of $360 — so she has $140 extra to direct strategically each month.
If Sarah Uses the Debt Snowball
Sarah targets the $800 retail store card first (smallest balance). At $24 minimum + $140 extra = $164/month, she pays that off in about 5 months. Then she rolls the $164 into the personal line of credit payment, continuing the process. Along the way she gets the win of watching that first debt disappear fast — a significant motivational lift when she’s just getting started and the path ahead still feels daunting.
If Sarah Uses the Debt Avalanche
Sarah targets the retail store card first anyway — and here’s a real-world quirk: in her case, the smallest balance ($800) also has the highest interest rate (29.99%). This is not uncommon. Many Canadians have retail store cards with sky-high rates and smaller balances. When this happens, both methods point to the same starting debt — and you get both the motivational win and the mathematical win simultaneously.
After paying off the retail card, the avalanche steers Sarah to the TD Visa at 20.99%, while the snowball would send her to the Personal Line of Credit at $3,100 (next smallest). Over the full payoff journey, the avalanche saves Sarah roughly $400–$600 in total interest compared to the snowball — meaningful, but not life-altering given her income and time horizon.
🍁 Canadian Tip: Check whether your highest-rate debt is also your smallest balance. When they’re the same debt, you get a free ‘snowball + avalanche’ combo — all the motivation, all the savings. |
Which Method Is Right for You? A Canadian Decision Guide
There is no universal winner here — the right method depends on your psychology, your debt mix, and your financial history. Use the table below to find your fit:
Choose Debt Snowball If… | Choose Debt Avalanche If… |
✅ You’ve tried paying off debt before and quit | ✅ You’re disciplined and spreadsheet-driven |
✅ You have many small balances (retail cards, BNPL) | ✅ You have one or two very high-rate debts |
✅ You need visible wins to stay motivated | ✅ You can stay motivated without quick wins |
✅ You’re stressed and overwhelmed by debt | ✅ You want to save maximum interest |
✅ Your interest rates are similar across debts | ✅ Your largest debt also has the highest rate |
The Hybrid Approach: Get the Best of Both
Some Canadian financial advisors suggest a pragmatic middle ground: start with one quick snowball win to build momentum (pay off your smallest debt), then switch to the avalanche method for all remaining debts. This gives you an immediate confidence boost without sacrificing much in interest savings over the long run.
This hybrid works particularly well if you have one very small, annoying debt (like a $300 store credit card) and then a couple of large, high-interest credit card balances. Clear the nuisance, feel the win, then go full avalanche.
🏆 The best debt strategy is the one you will actually complete. A ‘suboptimal’ method executed consistently will always beat a mathematically perfect method abandoned in month four. |
Canadian-Specific Considerations for Your Debt Strategy
While the snowball vs. avalanche debate applies everywhere, a few factors make the Canadian context unique:
Credit Card Interest Rates in Canada Are Exceptionally High
The standard rate on a Canadian credit card is 20.99% — one of the highest in the developed world. This makes the avalanche method particularly compelling for Canadians carrying large credit card balances, since the ongoing interest cost of delay is steep. A $5,000 credit card balance at 20.99% costs you over $1,000 per year in interest alone if you only make minimum payments. Source: MoneySense Canada
Buy-Now-Pay-Later (BNPL) Debt Is a New Reality
Younger Canadians are increasingly carrying BNPL debt from platforms like Afterpay, Klarna, and PayBright — often small balances with punishing penalty rates if missed. These are ideal snowball targets: small, achievable, and emotionally satisfying to clear. They also carry hidden costs that make avalanche treatment worthwhile if late fees apply.
Tax-Sheltered Savings vs. Debt: A Canadian Consideration
Canada’s TFSA and RRSP contribution room doesn’t roll over the same way American accounts do — especially RRSP deduction limits. Some Canadian financial planners suggest that if your debt interest rates are lower than expected investment returns (e.g., a line of credit at 7–8%), it may make sense to pay down debt while still contributing to a TFSA. However, for high-interest credit card debt above 15%, paying off debt first almost always wins. Always consult a certified financial planner (CFP) for personalized advice.
Provincial Debt Relief Programs
If your debt is unmanageable regardless of which repayment strategy you pick, Canada offers formal options including Consumer Proposals and bankruptcy protection, both administered by Licensed Insolvency Trustees (LITs). These are regulated processes under the Bankruptcy and Insolvency Act and may be worth exploring before taking on more debt to pay debt. Visit the Office of the Superintendent of Bankruptcy Canada.
Step-by-Step: How to Start Your Debt Payoff Plan Today
Regardless of which method you choose, the starting steps are identical. Here’s how to launch your debt payoff journey this week:
- Write down every debt you owe — balance, interest rate, minimum payment, and lender. Don’t skip any. Include credit cards, lines of credit, car loans, student loans, and BNPL balances.
- Calculate your monthly debt payments total (minimums) and compare to your take-home pay. Know your baseline.
- Find your ‘extra money.’ Review your last 3 months of spending and identify at least one area to cut — a subscription, eating out less, or pausing discretionary spending. Even $50–$100/month matters.
- Choose your method. Use the decision table above to pick snowball or avalanche based on your personality.
- Set up automatic minimum payments on all debts so you never miss one. Missed payments hurt your credit score and undo progress.
- Direct your extra money to your target debt every single month. Automate this if possible.
- Track your progress monthly and celebrate milestones — first debt paid off, halfway point, last debt under $1,000.
- Avoid adding new debt during your payoff period. Put credit cards in a drawer if needed.
Case Study: Two Canadians, Two Methods, One Goal
Case 1 — Marco, 29, Vancouver: The Snowball Skeptic Turned Believer
Marco had tried to pay off his four debts twice before and quit both times. He felt the avalanche made the most sense mathematically, but when he did the math and realized his highest-interest debt was a $6,800 credit card that would take 14+ months to clear, he lost motivation within weeks.
On his third attempt, his partner convinced him to try the snowball. He started with a $450 furniture store balance. It was gone in three months. Then a $1,100 personal loan. By month seven, Marco had paid off two debts and was making aggressive payments on a third — something he had never achieved before. He went on to become completely debt-free in 22 months.
“The psychology of it was everything for me,” Marco says. “The avalanche is smarter on a spreadsheet. But I couldn’t live on a spreadsheet for two years.”
Case 2 — Priya, 41, Toronto: The Disciplined Avalanche User
Priya had $28,000 in debt — mostly a $15,000 credit card balance at 20.99% and a $13,000 car loan at 6.5%. She sat down with a financial planner, ran the numbers, and went avalanche without hesitation.
“There was no contest,” she explains. “My credit card was costing me $260 a month in interest. Tackling it first was like giving myself a $260 raise every month I knocked down the balance.”
Priya stayed motivated by tracking her interest savings rather than her remaining balance — watching that monthly interest charge drop from $260 to $180 to $90 to $0 was satisfying in its own precise way. She was debt-free in 31 months and estimates she saved over $3,800 compared to the snowball approach given how large her high-interest balance was.
💡 The lesson from both stories: the method you can maintain is the one that works. Know yourself first, then choose your strategy. |
Conclusion: Which Method Works Better for Canadians?
After walking through both strategies, here’s the honest answer: neither the debt snowball nor the debt avalanche is universally ‘better.’ They’re tools — and like all tools, their value depends on who’s using them and for what purpose.
The debt avalanche wins on pure mathematics, especially in Canada where credit card interest rates of 20.99%+ are the norm. If you’re disciplined, can stay the course without frequent visible wins, and have one or two large high-interest balances, the avalanche will save you the most money.
The debt snowball wins on psychology and follow-through. If you’ve tried to pay off debt before and stopped, or if you have many small balances that make everything feel overwhelming, the snowball gives you quick wins that build genuine momentum. And momentum — not math — is what actually gets most people to the finish line.
For most Canadians, the recommendation is this: start by checking whether your highest-interest debt is also your smallest. If it is, both methods agree — and you’re already set. If not, honestly assess whether you’re a ‘Marco’ or a ‘Priya.’ Your track record with financial discipline is your best guide.
Whatever you choose, the most important step is the first one: listing every debt you owe and deciding to do something about it. That decision, made clearly and followed through consistently, is worth far more than choosing the mathematically perfect strategy and never executing it.
Canada’s debt load is real and growing. But so is the community of Canadians who are taking it seriously and building their way to financial freedom — one payment at a time.
🍁 Start your debt payoff plan this week. Pick one method, list your debts, find $50–$200 extra per month, and make your first strategic payment. The first step is always the hardest — and the most important. |
Key Takeaways
- The Debt Snowball pays off the smallest balance first; the Debt Avalanche targets the highest interest rate first.
- The avalanche saves more money in interest; the snowball provides more psychological wins.
- Adherence rates favour the snowball (~72%) over the avalanche (~58%) — completion matters.
- Canadian credit card rates (20.99%+) make the avalanche particularly compelling for high-balance credit card debt.
- A hybrid approach — one snowball win, then avalanche — can work well for many Canadians.
- If your highest-rate debt is also your smallest balance, both methods agree: pay it first.
- The best strategy is the one you will actually complete. Know your behavioural tendencies.
